Tag: Amio Bank

  • Sokolov’s Shadow: The “Straight Man” Behind Bank of London’s Cleanup

    September 17, 2026

    Bank of London is a British clearing bank and fintech company. It launched in November 2021 as the UK’s sixth principal clearing bank, entering the market with a $1.1 billion valuation.

    Historically, the UK’s clearing market was dominated by four major banking groups: Barclays, HSBC, Lloyds and RBS (now NatWest). They were later joined by ClearBank and, in 2021, by Bank of London (also known as The Bank of London; TBOL).

    An AI illustration inspired by the architecture of 77 Cornhill, London

    From the two 2025 audited reports of THE BANK OF LONDON GROUP LIMITED and its parent company, TBOL HOLDINGS UK LIMITED, filed with Companies House as of 18 August 2026 (PDFs available at the links above):

    Going concern:

    “The Board recognise that, notwithstanding the commitment and ability of ultimate parent company shareholders to inject capital… a material uncertainty over going concern exists as a result of additional funding requirements and there are significant doubts about going concern.”

    Qualified audit opinion from EY — two red flags:

    Share-based payments: “Owing to significant turnover of staff and inadequate record keeping creating challenges to the retrieval of historical data, the Directors have been unable to conclude on the completeness, accuracy and disclosure of the share-based payment scheme records.”

    Employment tax liabilities: “The Directors have also estimated the valuation, and based the accounting and disclosure of employment tax provisions arising from benefit in kind payments to employees, on the information they had available because of inadequate historical records.”

    Office closures and legal claims:

    “In October 2025, the Board decided to exit the Group’s Belfast office… impacted roles either relocated to London or transitioned to an outsourcing partner.”

    “Provision in respect of a lease termination dispute… estimated exposure approximately £600k. Paid £129k into the Northern Ireland court… final settlement uncertain.”

    The New York office was closed early. The London office at 77 Cornhill is the only one remaining, with the lease extended until 2031.

    Anthony Watson Achievement: Britain’s First Gay Bank Founder

    Anthony Watson’s story is not one of inherited privilege or a straight-line career. It is a story of a technologist who talked his way into banking, built a crypto exchange, and then founded a bank — while becoming one of the most visible LGBT+ figures in British finance.

    His first job was in technical support at AOL Europe, followed by First-e (Europe’s first internet bank), Microsoft, later CIO for Europe/Middle East at Barclays, where he co-founded the global diversity & inclusion panel. Then Uphold/Bitreserve (a crypto platform startup).

    He founded the project that launched as The Bank of London in November 2021. Companies House records show that Watson was a person with significant control and retained a 25–50% shareholding until April 2025. But Watson was not the one doing the quiet work. His key partner, Diane Elizabeth Gray-Smith, was the finance professional behind the early execution. As CFO at Uphold — the entity from which The Bank of London later emerged — she secured the Small Specialist Banking licence from the Bank of England before the 2021 launch.

    Watson was the first British citizen on the board of GLAAD (since 2013), ambassador for the charity Stonewall, chairman of the European Diversity Awards. In June 2023, he received a CBE “for services to the LGBT community, equality and diversity”. A Bank of London statement celebrating the award described him as ‘Britain’s only gay bank CEO’ and ‘the first LGBT person in Europe to found a bank.  It’s perhaps no surprise that with an openly gay CEO around 30% of senior leaders at The Bank of London identify as LGBT+. The Bank of London seeks to attract the “best diverse candidates for roles,” says Watson. “We don’t care if you’ve gone to university or not.”

    According to an investigation by The Critic, Watson donated £340,000 to Labour and Labour politicians. The largest recipient of his donations was Dawn Butler, Shadow Equalities Minister; in 2018, she made him the head of her equality advisory committee.

    Thus, Watson was the key founder and public face of the project, which had been developed for several years before The Bank of London launched in 2021. He stepped down as CEO in September 2024, as the bank entered a period of mounting financial and regulatory difficulties. He remained a shareholder and founder, however, and Companies House records show that he retained a 25–50% shareholding until April 2025.

    Watson lost not only the bank, but the “The” in its brand. “The Bank of London” remains a registered trading name, but in the bank’s current logo and public communications, the “The” has been cut off — leaving simply “Bank of London” (rebranded by Conran Design Group in Q2 2025).

    The Unicorn Bank Fed and Bled by Investors

    Watson was the face of the bank. But the financing came largely from outside investors. And among the investors behind the project, one name appears particularly early — Mangrove Capital Partners. Mangrove was involved with TBOL long before the Bank of London became a public-facing banking brand. CB Insights, a commercial database that tracks private companies, funding rounds and investors, lists Mangrove Capital Partners as the only recorded investor for a separate entry for the company “Tbol.” The dates attached to that database entry are inconsistent, so they should not be treated as definitive proof of an investment in 2018. But the connection is consistent with Mark Tluszcz, Mangrove’s managing partner, joining the company’s board on 25 April 2018. That makes Mangrove an interesting starting point for tracing where the money behind the Bank of London actually came from.

    November 2021 — $90 million Series C; $120 million raised to date. The Bank of London launched publicly with a $1.1 billion valuation, becoming what was described as the first pre-revenue bank to achieve “unicorn” status at launch. The latest round raised $90 million, led by ForgeLight, with follow-on investment from 14W Venture Partners and Mangrove Capital Partners. The company said it had raised $120 million in total by that point, with additional investment committed over the following 18 months.

    February 2023 — $40 million Series C extension. The new round came from existing investors and brought the reported total raised to $160 million. Mangrove Capital Partners and 14W Venture Partners co-led the round, with ForgeLight also participating. Alex Zubillaga, managing partner of 14W and a Bank of London board member, was quoted on the transaction. Mark Tluszcz was identified as both managing partner of Mangrove and a board member of The Bank of London.

    A coincidence worth noting. In February 2023, Harvey Schwartz became CEO of Carlyle Group — the firm co-founded by David Rubenstein, who also appears in our UChicago article. At the same time, Schwartz was Group Chairperson of The Bank of London. He had been associated with the bank since its launch.

    August 2024 — £42 million funding round led by Mangrove. The round was closed in August, shortly before the HMRC issue became public. Mangrove Capital Partners led the oversubscribed round, making it the lead investor at a critical point in the bank’s history. The funding was announced on 9 September — after Watson’s departure and almost simultaneously with the HMRC controversy. The money was raised before the crisis, not alongside it.

    September–October 2024 — the crisis becomes public. The bank faced an HMRC winding-up petition over unpaid taxes, while founder Anthony Watson stepped down as CEO and moved into an advisory role. Stephen Bell became CEO. The bank subsequently faced further scrutiny over its governance and capital position.

    2025 — restructuring under new control. By the time the bank’s later accounts were being discussed publicly, the company described itself as operating under new ownership, having secured £57 million of Mangrove Capital-led funding, with a further £25 million committed. That £42 million was part of a broader £57 million injection from new owners led by Mangrove. The new management described the period as a comprehensive transformation of the business.

    The Bank That Never Made a Penny

    The 2025 accounts show the scale of the problem. The Bank of London Group Limited, the operating bank, reported a £23.5 million loss in 2025, following a £23.9 million loss in 2024.

    At the Group level, the numbers are even worse. TBOL Holdings UK reported total income of approximately £6.4 million — including only £2.6 million in fee income — against a £27.0 million loss for the year. In 2024, the Group lost £46.9 million.

    The bank operates a full-reserve model: it does not lend, and all client monies are held in full and unencumbered at the Bank of England. Its revenue is primarily fee-based, supplemented by interest income.

    The contrast with the original launch story is striking. The bank entered the market with a $1.1 billion valuation, $120 million already raised, and plans to hire more than 3,000 people across the UK, Europe and North America. By 2025, the Group had approximately 86 employees, had never generated an annual profit, and had accumulated losses approaching £180 million.

    Who Are Today’s Owners Trying to Fix This?

    OPERATING ENTITY LICENSED BY PRA – FRN 930379   — THE BANK OF LONDON GROUP LIMITED, Company number 12844788 (formerly TBOL UK HOLDINGS LIMITED, 28 Aug 2020 — 08 Nov 2021).

    One active person with significant control is indicated: TBOL Holdings UK Limited.

    Current directors, according to Companies House — all six are also listed on the Bank’s official website:

    • BULLMAN, Antony George (CEO);
    • CARAWAN, Mark John (Independent Non-Executive Director & Chair of the Audit Committee);
    • HOWIE, Thomas Paul (General Manager & Executive Director);
    • MELIS, Anna Monique (Chairperson of the Board & Non-Executive Director);
    • MOECKLI, Alfred Walter (Non-Executive Member of Board);
    • WALKER, Simon Richard (Non-Executive Member of Board & Chair of Board of Risk Committee).

    PARENT HOLDING COMPANY – TBOL HOLDINGS UK LIMITED, Company number 10511092. Former names: OPLYSE HOLDINGS LIMITED (11 Mar 2025 — 20 May 2026); THE BANK OF LONDON GROUP HOLDINGS LIMITED (12 Oct 2022 — 11 Mar 2025); TBOL LIMITED (25 Apr 2018 — 12 Oct 2022); TBOL PLC (08 Nov 2017 — 25 Apr 2018); UPHOLD GROUP PLC (05 Dec 2016 — 08 Nov 2017).

    No active persons with significant control identified.

    Only current officers: DAVIDOFF, Ariel Sergio, Dr (Appointed on 27 April 2026); MOECKLI, Alfred Walter (Appointed on 7 April 2026).  Subscribers of our blog are already familiar with Swiss executives who have long-standing partnerships with Konstantin Sokolov and connections to Armenian AMIO Bank (1, 2). A quick look into the blog archives makes it clear: where you find this man, you find Konstantin Sokolov’s fingerprints.

    A small off-topic that helps better understand the shareholder composition below. In our blog, we have always associated Cypriot companies under Konstantin Sokolov’s control with the administrative company GIF Capital LTD (Cyprus), offering administrative services, with Iryna Sidiropulu as the key officer. According to the investigation by hetq.am (our English translation at the link), Konstantin Sokolov’s mother is Bronislava Gorelik. She appears personally as a director in the Cypriot companies IFG Basis Capital Limited (Cyprus, HE 454994) and BASIS CAPITAL INTERNATIONAL FINANCIAL GROUP LTD (Cyprus, HE 454996), but the secretary of these companies is CAPLATINE SECRETARIAL LTD. The parent structure, Caplatine Ltd (Cyprus, HE 450799) was established recently, on 30 August 2023, and is officially a licensed Administrative Service Provider (ASP) under the direct supervision and regulation of the Cyprus Bar Association (website).

    UPPER HOLDING COMPANY — TBOL HOLDINGS JERSEY LIMITED, Registration Number: 151277. Previous names: TBOL GROUP & HOLDINGS CORPORATION LIMITED (01/11/2023); FELLESSKAP GROUP & HOLDINGS CORPORATION LIMITED (11/02/2025 — 22/05/2026). Shareholders and owners are not disclosed in the public register. But the audited report 2025 of its UK subsidiary makes the power structure clear:

    “The long term and strategic decision making for the organisation is the responsibility of the Company’s parent company, TBOL Holdings Jersey Limited, and the Group Board implements the decisions made by the Board of TBOL Holdings Jersey Limited.”

    And now the most interesting part — our blog has obtained corporate records from Q2 2026 that allow us to determine with a high degree of certainty the controlling shareholder pool of TBOL HOLDINGS JERSEY LIMITED, with each shareholder holding less than 25% of the shares (below the threshold requiring disclosure).

    TBOL HOLDINGS JERSEY LIMITED SHAREHOLDERS:

    1. KONSTANTIN SOKOLOV
    2. BRONISLAVA GORELIK
    3. ANALIKA LIMITED (Cyprus, HE 456247) — director Adamos Adamides, who is also a director of CAPLATINE SECRETARIAL LTD; secretary: CAPLATINE SECRETARIAL LTD.
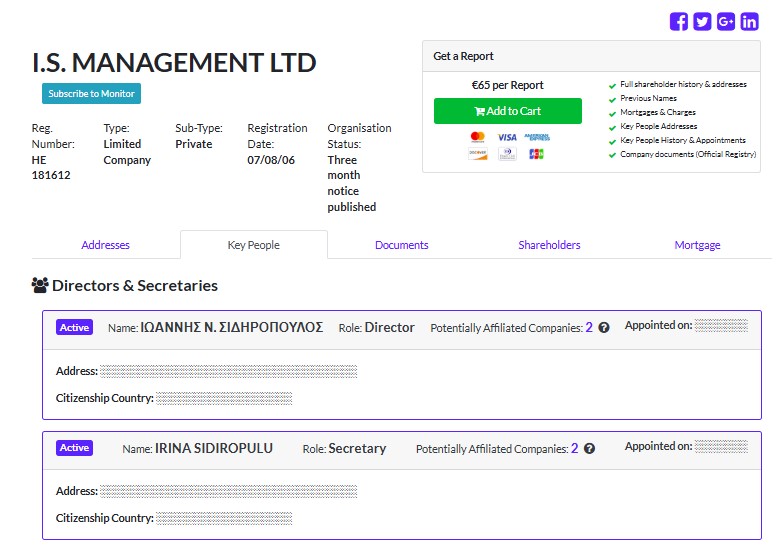
    4. ELISCANOUS LIMITED (Cyprus, HE 446650)— director Ioannis Sidiropoulos (same surname — relative (?) of Irina Sidiropulu (GIF Capital), together they manage I.S. MANAGEMENT LTD (Cyprus, HE 181612), secretary ALNIA SECRETARIAL LIMITED (see above, associated with Caplatine Secretarial Ltd.)
    5. PSINVEST CAPITAL LIMITED (Cyprus, HE 470533) — director and secretary Konstantinos Neophytou
    6. SOATA LIMITED (Cyprus, HE 466135) — director and secretary Kyriaki Ioannou
    7. BUSCELO LIMITED (Cyprus, HE 456243)— director and secretary Andreas Ourris
    8. Mangrove VI Investments Sarl (Luxembourg venture fund) — managers Hans-Jürgen Schmitz and Mark Tluszcz
    9. Mangrove V Investments Sarl (Luxembourg venture fund) — managers Hans-Jürgen Schmitz and Mark Tluszcz

    Thus, we associate shareholders 1–4 with Konstantin Sokolov and his business network.

    The UBOs of Cyprus companies 5–7 remain the mystery.

    Shareholders 8–9: Mangrove Group — among the very first investors.

    Interesting facts about Mangrove.

    1. Mark Tluszcz, founder of Mangrove Capital Partners, was a board member of TBOL Holdings UK Limited from 25 April 2018 — long before the public launch of the bank in November 2021 — and remained a director until 7 April 2026, when he left the board. Yet Mangrove entities — Mangrove V and Mangrove VI Investments Sarl, both managed by Tluszcz and Hans-Jürgen Schmitz — appear among the shareholders identified above. Tluszcz left the board; Mangrove remained in the capital.
    2. Mangrove Capital Partners and Index Ventures were among the early investors in Skype — before its sale to eBay in 2005. Giuseppe Zocco, co-founder of Index Ventures, is the spouse of Stephanie Rada Zocco, who joined the Board of Trustees of the University of Chicago together with Konstantin Sokolov. https://ksokolovarchive.cc/2026/09/10/uchicago-1-3-reputation-for-sale-sokolov-and-four-new-trustees/

    Don’t Mess with the US Donator

    Bank of London was never meant to make money. It was meant to be owned.

    For Konstantin Sokolov — a Russian financier who donated his way into the US elite after the Ukraine invasion — this is not new. A strange bank, a messy balance sheet, a licence worth having — and then, quietly, a rewrite of the books, a change of name, a new face. We have seen it with the Armenian AMIO Bank. We are seeing it again here.

    But look at the structure. Old investors stay. New ones appear. Sokolov’s people slip in between them. Nobody owns more than 25%. Nobody appears to control the bank — on paper. A perfectly fragmented cap table where no single name has to be disclosed.

    And yet, decisions are made. Somebody is making them.

    That is not a bank. That is a collection point — divided, diluted, and very carefully arranged.

    Credits:

  • How Halcon’s Portfolio Manager Is Linked to Dr. Zhe Zhang and Konstantin Sokolov

    August 06, 2026

    According to the pitch book for the Gotthard Investment Fund 2015 a Liechtenstein-based fund for professional investors (a critical update: the fund was subsequently liquidated in July 2020, with Ernst & Young approving its final closing balance sheet), managed by VP Fund Solutions AG – Konstantin Sokolov served as Vice Chairman and managing partner at Gotthard Investment AG in Switzerland, alongside his Swiss partner Roland Raeber. Together, they acted as Fund Managers of Gotthard Investment Fund / Gotthard Umbrella Fund signing off on all the fund’s transactions.

    Today, for an American citizen and a close associate of Donald Trump, direct affiliation with a European fund is no longer comme il faut. New projects require new partners and new instruments.

    In early 2024, we republished HETQ.AM’s investigation into the new owners of MTS Armenia. That investigation first revealed Sokolov’s new partner: the Chinese entrepreneur Zhe Zhang, and his connection to the management of Halcon Investment SICAV through SIFT Capital Partners Limited. That fund, in turn, controls AMIO Bank via the Cypriot company Elguma Investment Ltd. and Swiss MFM Global AG.

    ChatGPT generated group picture of Konstantin Sokolov, Dr. Zhe Zhang, and Michael Stockford.

    The Switch: SIFT out, Blue Water in

    In the publicly available reports for 2024 and 2025, SIFT Capital Partners Limited is no longer listed as the portfolio manager for Halcon Investment Fund. In its place: Blue Water Capital Management Limited.

    Did Zhe Zhang simply disappear? We think not. Blue Water Capital Management Limited, with its CEO Michael Stockford, is closely tied to Zhang – and, through him, to Sokolov.

    What did Blue Water do for Halcon Innovation Fund investors in 2025?

    The 2025 Halcon report includes a notification that the delegated portfolio manager changed its name from Redbridge Capital Management Limited to Blue Water Capital Management Limited.

    The fee structure is revealing. According to Halcon’s 2025 accounts, Blue Water’s total remuneration was HKD 7.237 million (≈ USD 928,000). Within that, the “Asset Management & Investment Advisory” fee specifically for the Halcon Innovation Fund was €305,729 – a reasonable and transparent charge.

    Blue Water also signed two major loan agreements in 2025 on behalf of Halcon: €13.7 million to MFM Global Invest AG (seemingly for the acquisition of a Swiss hotel) and €24.9 million to Remido Holdings Ltd – both entities connected to the wider Sokolov–Zhang ecosystem, as we previously covered.

    Effective 16 April 2026, the fund introduced two new unit classes as follows: HIF-EUR1M — for large institutional investors (minimum €1 million) — and HIF-DIRECT, a direct class for retail or qualified investors.

    Alongside these, the fund also adapted its Liquidity Management Tools to comply with new European regulations, which include a redemption-in-kind option.These changes may look like standard regulatory housekeeping. But they quietly give the manager new tools that can shift the rules of the game. New investors could find themselves locked into less favorable redemption terms, or — in the case of redemption-in-kind — receive assets instead of cash when they try to exit. In a fund already opaque and heavily invested in illiquid projects, this adds another layer of unpredictability for newcomers.

    What Blue Water Capital Management actually does

    According to its website, Blue Water works exclusively with Professional Investors as defined under Hong Kong’s Securities and Futures Ordinance (individuals with at least HKD 8 million – roughly USD 1 million – in securities). It holds SFC licences Type 4 (advising on securities) and Type 9 (asset management), registration BAU760, and operates under Hong Kong law.

    Blue Water does not manage the fund directly. It acts as a delegated portfolio manager. Its direct client is not the end-investor in Liechtenstein, but the fund’s management company – ONE Funds AG (registered in Liechtenstein). ONE Funds AG, as a licensed AIFM, hires Blue Water to manage the Halcon Innovation Fund portfolio. Crucially, Blue Water signs all decisions and contracts on behalf of the fund – a standard practice for such delegated structures.

    The Hatcher Group deal: Stockford and Zhang help Tanner consolidate control

    In early 2025, a deal on Hong Kong’s GEM exchange would have gone unnoticed – if not for its architecture. Hatcher Group Limited – a boutique consultancy specialising in taking Chinese mainland companies public – changed its controlling shareholder. Formally, through a standard rights issue. Informally, through a three-party operation where each participant played a distinct role.

    Hatcher Group is not a financial giant. It is a boutique firm with 100–150 employees, formerly known as VBG International Holdings. Its business: guiding mainland companies through the Hong Kong listing process – IPO advisory, M&A, corporate finance, ESG reporting. Listing was a pragmatic step, giving it access to public capital and strengthening client trust.

    That same public status made Hatcher Group a target.

    The buyer was Tanner Enterprises, controlled by Hong Kong businessman Li Man Keung Edwin. His goal: to increase his stake from 10.62% to a controlling position. The instrument: a rights issue with underwriting.

    Tanner agreed to buy any shares not taken up by existing shareholders. The risk was obvious: if the market didn’t support the deal, Tanner would get the company – but at a full price. If someone else tried to intercept the package, Tanner would get nothing.

    To rule out the second scenario, Michael Stockford was brought in – founder of Redbridge Capital Management Limited (later renamed Blue Water Capital). Stockford became an executive director of Hatcher Group on 1 October 2024. His companies served two roles: fund manager for the subscriber and placing agent for unsubscribed shares – at zero commission.

    The crucial element, however, was SIFT Capital Partners Limited – the Hong Kong asset manager founded by Zhe Zhang. SIFT subscribed to convertible bonds in Hatcher Group worth HKD 5.67 million, convertible into 18 million shares (up to 42% of the company). Formally, this was an independent transaction. In practice, it was a safety net.

    As long as SIFT held the bonds, any outsider eyeing control knew that Zhang could convert at any moment and dilute their stake. This wasn’t a blocker – it was a deterrent. And it worked in Tanner’s favour.

    When the rights issue closed, Tanner Enterprises had taken 65 million unsubscribed shares, raising its stake to 48.63%. Consolidation was complete. SIFT never converted – the bonds were never needed. Stockford stayed on the board, and his Redbridge soon rebranded to Blue Water Capital Management.

    Official documents from the Hong Kong Stock Exchange (HKEX) – the Hatcher Group Circular dated 10 January 2025 – neatly separate the participants: Zhang as the subscriber’s ultimate beneficial owner, Stockford as the owner of the management company, Tanner as the underwriter. There are no formal ties between them. But the logic of the deal suggests otherwise: three parties, synchronised in one process, with one goal – transferring control of a public company.

    Source: Hatcher Group Limited Circular, 10 January 2025 (HKEX). Page 43. The same document names Redbridge Capital Management (Michael Stockford) as the investment manager and Dr. Zhe Zhang (SIFT Capital Partners) as the ultimate beneficial owner of the CB Subscriber.”

    This is not collusion in the legal sense. It is a coordinated operation, where everyone knew their role. And the coincidences – the rebranding of Redbridge at the same time as the deal closed – are at the very least significant.

    After reading this brief account, one thing becomes clear: Blue Water Capital is far from a stranger to the shareholders of VIVA Armenia and AMIO Bank. It couldn’t be otherwise. The chain is consistent: Sokolov’s old Swiss structure, Zhang’s SIFT Capital, Stockford’s Blue Water – they all converge around the same assets. The rebranding, the appointments, the loans, the consolidation – all point to a stable, if informal, network operating across jurisdictions, from Liechtenstein to Hong Kong, via Cyprus and Armenia.

    Disclaimer & Forward-Looking Analysis: This article is for informational and educational purposes only and does not constitute legal, financial, or regulatory advice. All findings, linkages, and conclusions presented herein represent the authors’ analytical opinions, derived solely from the chronological correlation of verified dates, cross-border corporate filings, and publicly available disclosures from the Hong Kong Stock Exchange (HKEX) and the Liechtenstein Financial Market Authority (FMA). Unless explicitly cited from official regulatory documents, any inferences regarding parallel intent, nominee status, or informal networks are speculative hypotheses intended to stimulate public interest and independent analysis. This material does not accuse any mentioned individual or corporate entity of legal non-compliance, regulatory violations, or market collusion.

  • Mesrop Manukyan (MP, Armenia Alliance) to Ruben Rubinyan (Candidate for Speaker): Alleging Sokolov-Linked Conflicts of Interest in Banking, Telecom and Mining

    August 2, 2026 (transcript of a parliamentary speech originally delivered in Armenian; video published by Yerevan Today on YouTube)

    During the first session of Armenia’s 9th convocation of the National Assembly, opposition MP Mesrop Manukyan delivered a sharp critique of ruling-party candidate for Speaker, Ruben Rubinyan. Manukyan drew comparisons between the financial trajectories of former Speakers Ararat Mirzoyan and Alen Simonyan and the current candidate, alleging conflicts of interest tied to Rubinyan’s brother’s positions in banking and telecommunications, as well as the growing influence of businessman Konstantin Sokolov in Armenia’s strategic sectors. Manukyan concluded that Rubinyan overshadows his predecessors, calling him the “octopus” of the Civil Contract party.

    Full Translation from Armenian to English:

    “Dear citizens, those who have held the position of Speaker of Parliament from the Civil Contract party have undergone certain transformations. I would like to delve a little deeper into this and understand, Mr. Rubinyan, from what point you started and where you will end up.

    Ararat Mirzoyan once spoke of his financial difficulties, of being denied credit to purchase a television. Today, he walks about in a Brunello Cucinelli vest worth several million drams. In Yerevan, near the Red Cross, he is acquiring a mansion — this is from his declaration.

    Now, I see no issue with a high-ranking official of the Republic of Armenia — and that includes you, Mr. Rubinyan — presenting themselves with dignity, as they represent the state. However, the question arises: how do these transformations take place? Similar questions have also emerged regarding former Speaker of the National Assembly Alen Simonyan. His property transactions have become a matter of public discussion.

    Now let us turn to you, Mr. Rubinyan. You have stated that since late 2021, you have been a member of the negotiation group with Turkey — this is well known. In 2022, Haybusiness Bank was acquired by a Swiss company, and the state became a 25% equity shareholder. The press has speculated that this is linked to Konstantin Sokolov. Today, Sokolov has entered our Armenian life, our Armenian reality. I will note an interesting fact: Ruben Rubinyan’s brother is today the First Deputy Chairman of the Management Board of Amio Bank CJSC and Chief Business Development Director, as well as a member of the board.

    Here is an interesting point: is there not a conflict of interest in the Central Bank being an equity shareholder in a commercial bank? In other words, how can the Central Bank go and audit this company? But I will set that aside and continue, as I have much more to say.

    In 2023, Mr. Rubinyan, MTS Armenia submitted an application to purchase from some offshore-registered auto dealer — I apologize for the phrasing, as this individual, if I am not mistaken, is a certain 50-year-old Manolis Tarkhanadis from Cyprus, who was engaged in car trading but wished to acquire a mobile operator in Armenia. They were refused on national security grounds.

    However, in 2024, when Fedilco Limited — whose beneficiary is also Konstantin Sokolov — appeared, they acquired the assets. And here is an interesting development: following the deal, Levon Rubinyan was appointed to the management board of Viva Armenia.

    Next, we see that the Hrazdan Cement plant is owned by Amio Bank. Citizens, this is a commercial organization with state participation — the state should have managed it directly. It is heading toward bankruptcy, and there is state involvement here because it belongs to Amio Bank, where Levon Rubinyan is present.

    The next notable transaction: Rostelecom is acquired, Viva Armenia is acquired. Two major operators are being purchased, and on the management board of the very same Viva Armenia sits Levon Rubinyan.

    Is this normal?

    Furthermore, the same Sokolov was appointed chairman of the TRIPP fund. There is also information that he acquired a stake in our mining giants.

    We have identified four critical sectors: finance, infrastructure, mining, and telecommunications. For any state, these are sectors of strategic and defense significance — and in Armenia’s case, they are of particular importance to Turkey. And here the question arises: the TRIPP project manager Sokolov, with Turkey being the largest beneficiary of these projects, on one hand — and on the other hand, the brother of Armenia’s chief negotiator with Turkey is deeply involved in these processes.

    Is this strange or not?

    Mr. Rubinyan, I will speak honestly: I have tried to understand where Alen Simonyan and Ararat Mirzoyan started and where they have ended up. At this point, I cannot even identify your starting point. And it creates the impression that Alen Simonyan and Ararat Mirzoyan are small fish compared to you. You are the octopus of the Civil Contract — that is the impression I get, a sea monster. And this is not personal — it is a political assessment.”

  • HETQ.AM Trump’s Generous Donor to the Republican Party Appointed to Head the TRIPP+ Fund

    July 20, 2026 (brilliant article from HETQ.AM, author Vahe Sarukhanyan, published as of 17/07/2026)

    Konstantin Sokolov, who donated $11 million last year to the MAGA committee supporting U.S. President Donald Trump, has been appointed head of the U.S. government-backed TRIPP+ Enterprise Fund, which plans to invest $201 million in the South Caucasus and Central Asia. What does this appointment mean for Armenia, and who is really behind Armenia’s largest mobile telecommunications asset?

    Konstantin Sokolov is a U.S. citizen of Jewish descent and a businessman originally from St. Petersburg. His name has once again become the subject of widespread media attention—not because of his business activities this time, but because of politics.

    $201 Million for the Private Sector in the South Caucasus and Central Asia

    According to The Guardian, citing a spokesperson for the U.S. Department of State, the TRIPP+ Enterprise Fund—named after the TRIPP (Trump Route for International Peace and Prosperity) initiative—has been authorized to invest $201 million in the private sectors of the South Caucasus and Central Asia. The fund will operate in Armenia, Azerbaijan, Georgia, Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan, and Uzbekistan.

    The investments are intended to promote the strategic development of the private sector in these countries and may take the form of loans, equity investments, and grants.

    TRIPP+ Is Not the Manager of the TRIPP Project

    To avoid confusion, it is important to note that the TRIPP+ Enterprise Fund is not responsible for managing the TRIPP project itself.

    A joint document published on January 13, 2026, by the foreign ministries of Armenia and the United States, revealed that the two countries will establish the TRIPP Development Company, which will oversee the implementation and infrastructure development of the TRIPP project.

    Under the agreement, 26% of the company will be owned by Armenia, while 74% will belong to the United States, specifically to TRIPP Development Company US, which will be incorporated in Delaware as a subsidiary of the U.S. International Development Finance Corporation (DFC).

    Armenia and the United States initiated the strategic cooperation agreement on the implementation of TRIPP on May 26, 2026, in Yerevan, and formally signed it remotely in June.

    During the Armenian government’s meeting on July 16, Foreign Minister Ararat Mirzoyan explained that:

    “An American investment company called TRIPP+ is being established to attract investments for the implementation of the project. Legally, it has an indirect relationship with our TRIPP Development Company. The head of the American investment company TRIPP+ has already been appointed.”

    Mirzoyan was referring to Konstantin Sokolov.

    Why Was Konstantin Sokolov Chosen?

    According to The Guardian, which cited four U.S. foreign assistance experts, appointing politically connected individuals to the boards of Enterprise Funds is common practice for the White House.

    Former Enterprise Fund official Don Niss noted that while such appointments are understandable, problems arise when politically connected appointees lack experience in investment banking, private equity, or the sectors in which the funds will invest.

    In Sokolov’s case, however, his professional background appears to support his appointment.

    According to his official biography, the 51-year-old businessman has led restructuring projects for sovereign wealth funds and central banks, steered the listing of firms on all major stock exchanges and provided strategic counsel to governments and major companies. 

    One notable detail, though, is absent from his official biography.

    According to records from the U.S. Federal Election Commission, Sokolov has become an active political donor.

    While he contributed only $3,600 to Barack Obama’s presidential campaign in October 2008, in 2025 he donated $11 million to the MAGA (Make America Great Again) Committee supporting President Donald Trump. In March 2026, he contributed another $443,000 to the Republican National Committee.

    Notably, according to FEC records, Sokolov made political donations only twice: once in 2008, and then again beginning in 2025.

    Beyond his support for President Trump and the Republican Party, Sokolov is also among the 36 donors who contributed to the construction of the new White House Ballroom. Although the amount of his personal donation has not been disclosed, President Trump has stated that donors collectively contributed more than $350 million to the project.

    Sokolov’s Footprint in the Armenian Economy

    Hetq first wrote about Konstantin Sokolov in early 2024, when it was officially announced that he had become one of the beneficial owners of Viva Armenia, the country’s largest mobile telecommunications operator.

    However, Hetq had obtained information about both Sokolov and the company’s other ultimate beneficial owner, Chinese national Zhe Zhang, several months earlier, in 2023.

    In April 2023, Armenia’s Public Services Regulatory Commission (PSRC) refused to approve the transfer of control over MTS Armenia (now Viva Armenia).

    The company’s Russian parent, MTS, sought to sell its Armenian subsidiary, but the PSRC referred the proposed transaction to the Ministry of High-Tech Industry, which in turn consulted the National Security Service (NSS). The state bodies ultimately objected to the deal, concluding that approving it would harm—or could potentially harm—Armenia’s national security or state interests.

    According to a Hetq source, the authorities rejected the transaction because they were unable to identify the ultimate beneficial owner of the acquiring entity. The lack of transparency regarding who would ultimately control Armenia’s largest mobile operator was considered a security risk.

    Later, Sokolov and Zhang emerged through their Cyprus-registered companies.

    According to Hetq’s source, they stated that the funds intended for the acquisition of MTS Armenia would come from their family trusts. However, the origin of those assets, the nature of the trusts, their activities, and other essential information were never adequately disclosed.

    Eventually, Armenian authorities approved the transaction in November 2023. Ownership of MTS Armenia officially changed in January 2024, with Zhe Zhang becoming the ultimate beneficial owner of 75% of the company and Konstantin Sokolov acquiring the remaining 25%.

    In February 2024, the new owners donated a 20% stake in Viva Armenia to the Armenian government. As a result, Zhang’s ownership was reduced to 60%, and Sokolov’s share became 20%.

    The Armbusinessbank Deal

    Hetq also reported on the sale of Armbusinessbank (now AMIO Bank), 75% of which was acquired by a Swiss investment fund owned by a fund registered in Liechtenstein. The management of latter had been delegated to a Hong Kong company owned by Zhe Zhang.

    According to Hetq’s source, Sokolov acted as a representative and adviser to the foreign funds that owned the bank.

    The source further explained that Zhang and Sokolov essentially specialize in arranging corporate acquisitions. Their role includes organizing negotiations, coordinating transaction terms, representing the actual beneficial owners—rather than serving as the beneficial owners themselves—executing transactions, and submitting documentation to the relevant government authorities.

    Hetq subsequently reported on several earlier transactions involving Sokolov. One of them concerned a Canadian investor who filed a lawsuit in a Cypriot court against his Russian business partners, seeking to recover $2.5 million in investments.

    Although the Canadian investor ultimately lost the case, the story attracted attention because an article about it was later removed from a Cypriot news website, though an archived version remained available.

    Following Hetq’s publication, there was also an unsuccessful attempt to have the newspaper’s article removed from Google Search.

    It is perhaps no coincidence that shortly after becoming a beneficial owner of Viva Armenia, Sokolov launched his personal website on February 5, 2024. The site presents his biography, personal story, philantropy, and other information.

    The move creates the impression that a businessman about whom very little had previously been known—and whose online presence largely consisted of reports about investment disputes and an unsuccessful investment project in Russia—sought to establish a more positive public profile after acquiring a stake in Armenia’s largest mobile operator and to dispel some of the mystery surrounding his background.

    According to Hetq’s sources, Sokolov is highly sensitive to public reporting about him, particularly criticism related to his business activities.

    What Is an Enterprise Fund?

    An Enterprise Fund is a financial mechanism established by the U.S. government, with origins dating back to 1989, when the U.S. Congress passed the Support for East European Democracy (SEED) Act.

    The initiative was designed to promote private-sector development in former socialist countries as they transitioned to market economies.

    The first Enterprise Funds were created for Poland (1990), Hungary (1990), Czechoslovakia (1991), Bulgaria (1992), Romania (1994), the Baltic states (1995), and Albania (1995). Since 1989, the U.S. government has established 13 Enterprise Funds.

    Financial Status of U.S. Government-backed CEE Funds as of September 30, 2003

    Each fund operates as an independent, autonomous organization governed by its own board of directors, while the U.S. government oversees its activities.

    According to the U.S. Department of State, this model was specifically designed so that the Funds could deliver assistance as rapidly as possible, with enough flexibility to develop programs and use a variety of investment approaches to address specific conditions in each country.

    Credits: https://hetq.am/en/article/182743

  • Halcon Innovation Fund posts 11.94% NAV Drop After AMIO Bank Corrections in 2025

    July 09, 2026

    We have been following the Halcon Investment SICAV (an alternative investment fund (AIF) for professional investors under Liechtenstein law in the legal form of an investment company with variable capital managed by ONE Funds AG) and its connection to AMIO Bank and Konstantin Sokolov—the man behind the newly renamed Sokolov Executive MBA Program at Chicago Booth—for some time now. The connection was first identified in 2024 by Armenian investigators from hetq.am.

    By mid-2026, the annual reports for both Halcon Investment SICAV and AMIO Bank for the year ending December 31, 2025 became publicly available. They contain significant new information that we are now ready to partly analyze.

    Halcon’s 2025 Report: Structural Consolidation and a Major Write-Down

    The most visible change in Halcon’s 2025 annual report is structural. Of the five sub-funds that previously operated under the Halcon Investment SICAV umbrella, four — XTech Investment Fund, Arami Capital Fund, Gingolph Capital Fund, and Antarctic Investment Fund — are now marked as “in liquidation” (i.L.). Only the Halcon Innovation Fund, which stands behind MFM Global AG (subsidiary of Elguma Investment Limited)— the major shareholder of AMIO Bank — remains active. This means all remaining assets and liabilities are now concentrated in a single vehicle.

    BDO (Liechtenstein) AG, a mid-tier international audit network, reported a drop in the fund’s total assets from €118.7 million at the end of 2024 to €93.7 million at the end of 2025. But the more significant disclosure concerns a post-closing adjustment. After the December 31, 2025 reporting date, the fund identified a material error in the valuation of its investment in AMIO Bank. The correction amounted to €24 million, leading to a mandatory restatement of the net asset value.

    The originally reported NAV per unit of €1,650.10 was revised downward to €1,309.94, representing an 11.94% decline in the fund’s value over the course of 2025.

    What Triggered the Correction: AMIO Bank’s 2025 Report

    The correction in Halcon’s accounts was not an independent event. It was triggered by the 2025 financial statements of AMIO Bank itself, audited by Baker Tilly Armenia, a member of the Baker Tilly International network, one of the top eight global accounting networks.

    In Note 3.4 of its report, titled “Changes in Accounting Policy and Presentation / Error correction,” the bank formally acknowledged a major retrospective error. The misstatements related to two critical areas: the fair value assessment of foreclosed properties and the calculation of expected credit losses on loans for periods prior to 2023.

    The cumulative effect was substantial. As of December 31, 2023, the bank’s retained earnings were restated downward by 23.55 billion Armenian drams (approximately $58.9 million at the 31.12.2025 exchange rate of 1 USD = 399.82 AMD) — from a loss of 20.3 billion drams (approximately $50.8 million) to a loss of 43.9 billion drams (approximately $109.8 million).

    The 2025 report also confirms a capital replenishment of 20 billion Armenian drams (approximately $50 million), registered by the Central Bank of Armenia in February 2025. This appears to be a move to meet regulatory capital requirements — a detail worth noting as we continue to examine the bank’s financial trajectory.

    This is not a minor adjustment; it is a comprehensive rewrite of prior years’ financials. And it raises an obvious question: these are not random accounting errors. The pattern is familiar — we have seen this before. In 2021, before the change in ownership, Armbusinessbank (as AMIO Bank was then known) recorded a significant income tax refund that inflated its balance sheet and improved its apparent financial health. This accounting maneuver — effectively a bookkeeping benefit — made the bank look more attractive to prospective buyers. After the ownership changed, the benefit was reversed, and the bank had to recognize a corresponding tax expense. That previous correction, like this one, involved material adjustments to reported earnings and served to improve the bank’s valuation at a critical moment.

    According to Note 16 of the bank’s 2025 financial statements, AMIO Bank exhibits a high concentration of credit risk, with AMD 159,721,076 thousand (approximately $399.5 million at the 31.12.2025 exchange rate) due from just its ten largest third-party borrowers and their related parties.

    Furthermore, in Note 2 (“Business Environment”) of the AMIO Bank report, management — led by Chairman Gevorg Tarumyan — formally acknowledged external geopolitical risks. The bank stated that the U.S. and Israeli military strikes on Iran of February 28, 2026, could have consequences for Armenia’s economy and the banking sector. Given these factors, is a further decline in valuation anticipated?

    A Bridge to the Next Investigation

    The 2025 reports raise several questions that we will address in the upcoming articles of this series.

    First, the fund’s portfolio structure has changed significantly. New non-banking investments were made to a lifestyle business hotel near Zurich Airport — a connection we first suggested in February 2026. At the same time, the fund’s management has explicitly highlighted its real estate projects in Cyprus as a core investment focus, and details have become clearer.

    Second, the fund has introduced two new share classes — HIF-EUR1M and HIF-DIRECT — effective April 16, 2026. The fund also updated its Liquidity Management Tools and added a clause on Redemption in kind. These changes raise questions about the fund’s strategy and target investor base.

    Third, we will examine the role of Blue Water Capital Management Limited in Halcon Innovation Fund management, the Hong Kong-based portfolio manager, and its connection to Dr. Zhe Zhang, a key figure who has repeatedly surfaced as a frontman for American businessman Konstantin Sokolov.

    We will address these questions in the next articles of this series. And perhaps, as we do, we might pose a broader question to the students of Konstantin Sokolov’s Executive MBA Program in Chicago: “If the numbers change after the deal is done, were they ever real in the first place?”

    Credits:

  • Second Swiss Departure: Ariel Sergio Davidoff Leaves AMIO Bank’s Supervisory Board

    Another Swiss executive has quietly exited an institution rumoured to be linked to Konstantin Sokolov. On current date, AMIO Bank’s official website no longer lists Ariel Sergio Davidoff as a Supervisory Board Member. No official statement has been issued.

    Source: amiobank.am/en/managers (screenshot taken June 5, 2026). Davidoff’s name is absent.

    Davidoff, a Swiss senior manager, became a Supervisory Board member and Chair of the Audit and Risk Committee in 2023, after the bank’s acquisition by MFM Global Invest AG. The bank was later rebranded as AMIO Bank.

    Following his appointment in 2023, Davidoff gave an interview to the bank’s press service titled “When Development is a Priority, the Risk is Worth Taking” presenting himself as part of the new management team.

    Our blog previously wrote about Davidoff on February 15, 2026, in “The Russian Connection: The Mystery Men Behind Armenian AMIO Bank — and Zurich’s Glitziest Hotel”.

    This marks the second Swiss national to leave a Sokolov-linked entity. The first was Gerard Hofmann, who departed in 2024.

    In preparation of this note, we cross-checked the information with the Swiss commercial register as well as with the archived version of AMIO Bank’s website. The bank’s own site, as of 23 January 2026, still listed Davidoff as a member of the Foundation board of the Swiss Russian Forum Foundation (2021 — present). However, according to the Stiftung Swiss Russian Fund entry in the Swiss Commercial Register (Handelsregisternummer CH-020.7.001.401-4, UID CHE-113.330.890), Davidoff had already resigned from that foundation’s board on October 16, 2022 — eight months after the full-scale Russian invasion of Ukraine — and is no longer listed as a member.

    Why does this matter? For top white collar Swiss professionals seeking “clean” money, Russian linked business has become increasingly toxic.