Viva and Amio Bank (Armenia) bring to you yet another joint offer…
Take advantage of Viva’s tariff plan, get a free Amio-Viva digital Mastercard and don’t pay to stay connected until 31 March 2027.
Using Viva tariff plans is always more than just communication…
Take advantage of Viva’s proposed tariff plans from 10 September 2026 to 31 March 2027 (inclusive), receive a free Amio-Viva digital Mastercardand do not pay for services provided under the tariff plan during the offer period.
go to the Amio Bank website via the “My Viva” application,
follow the prompts to apply for a free Mastercard digital card on the Amio Bank website.
And after receiving the card, do not make the upcoming payment to use your tariff plan.
Moreover, if you make at least 20 transactions of at least AMD 1000 each with your Amio-Viva digital Mastercard during the 30 days preceding the payment during the offer period, or a total of at least AMD 50 000 transactions during the same period, you will continue to use your Viva tariff plan without paying.
In other words, if the above condition is met within 30 days prior to the payment scheduled for using the tariff plan, the subscriber does not pay the price for the next activation of the prepaid tariff plan/monthly fee for the postpaid tariff plan**.
** If the condition within the scope of the offer is met, the price of the next activation of the prepaid tariff plan/monthly fee of the postpaid tariff plan is paid by Amio Bank.
The history of the president’s political career is so thoroughly shot through with various Russians that it’s a wonder that the Bolshoi isn’t doing three shows a night in the East Room. It is, of course, all a hoax according to the administration. That lasts until the next Volga Bagman shows up in the news.
Photo: Donald Trump — a distorted image. Credit:Pau Casals/ Unsplash Source:Unsplash
We’re all still digesting the news that a Russian oligarch paid for the after-party at Junior’s wedding, and here comes the good folks at the International Consortium of Investigative Journalists with another entry in the accidental Russian derby.
A company linked to a major Trump donor received authorization from the Treasury Department to complete an acquisition involving a sanctioned Russian bank, according to public records. The Texas-based Dynamic Frontier Holdings purchased Teghut, one of Armenia’s largest copper mines, this summer. Dynamic Frontier’s manager is Konstantin Sokolov, a Russian-American businessman who was one of three dozen private donors to …
… wait for it …
President Donald Trump’s $350 million White House ballroom project.
That damned ballroom again. It is the key to so much of the White House corruption. Every editor of every newspaper should get on a big bus and drive to DC and look at the gouge in the land where the ballroom is supposed to be. There are something like 20 Pulitzers down in there waiting to be found.
Russia’s state-owned VTB Bank was Teghut’s primary shareholder and creditor prior to the purchase. The U.S. Treasury Department sanctioned VTB Bank following Russia’s invasion of Ukraine, describing it as a “critical artery” of the country’s financial system. The sanctions prohibit U.S. companies and individuals from transacting with VTB Bank. But on September 3, Dynamic Frontier said in a press statement that it had “received authorization from the U.S. Department of the Treasury” on June 1 to acquire all of Teghut’s shares and outstanding debt.
The Treasury Department’s Office of Foreign Assets Control, known as OFAC, can grant a license to individuals or companies to complete transactions that would otherwise be prohibited by sanctions. OFAC states on its website that it may grant a license to do business with sanctioned Russian entities when it is in the interest of the applicant and the U.S. government.
I think that, in this case and in so many others, “the applicant” and the U.S. government ought to have radically different “interests.” Da.
Last week, while checking the U.S. trademark database, we noticed something rather difficult to miss. Between August 31 and September 4, 2026, seven trademark applications were filed under the name of Konstantin Sokolov.
KONSTANTIN SOKOLOV MEDIA — Serial No. 50091801, Classes 009, 035, 038, 041 and 045 — $1,750 paid
KONSTANTIN SOKOLOV ARCHIVE — Serial No. 50091778, Classes 009, 035, 038, 041 and 045 — $1,750 paid
The two media-related applications are the ones that caught our attention. Both cover the same five classes: downloadable recordings and software; advertising and business services; telecommunications and streaming; education, entertainment and media production; and intellectual-property and copyright management.
In other words, this is not simply an application for a logo.
It is a fairly broad attempt to protect a name across digital content, media, communications and related intellectual-property activities.
A Long Road to a Trademark — There and Back
The filings are handled by Yuming (Violet) Zhang (“Zhang” is also the surname of Sokolov’s business partner Dr. Zhe Zhang, but since it’s one of the most common surnames in China, we’ll call it an ironic coincidence, probably ) of Buchalter LLP — a full-service business law firm founded in 1933, with offices including Chicago. The firm has its own history of courtroom mishaps: a $147,000 sanctions bill in 2023 for “misleading statements under oath,” and a November 2025 case involving AI-fabricated citations slipping into a federal filing.
None of the seven filings is currently a registered trademark. All seven show the USPTO status “630 — New Application — Record Initialized Not Assigned To Examiner.” The applications have been received, but they have not yet been assigned to an examining attorney.
So, legally speaking, nothing has been registered yet.
But Konstantin Sokolov filed them. All seven. And one of them is for a name very close to this site’s.
Under current USPTO timelines, a new application is typically assigned to an examiner within six to eight months of filing. From there, the process can take another year or more — through examination, publication, and a 30-day opposition window — before any registration is issued. None of that has started yet for the seven filings. The applications have been received. They have not been reviewed.
Many Millers. Many Sokolovs.
There is another detail worth mentioning. «Sokolov» is to the Slavs what «Miller» is to America — one of the most common surnames, shared by millions.
“Konstantin Sokolov” is not a unique name. There are other good people with that name working in completely different fields — including science, art, professional sport and technology.
One is Konstantin Sokolov, a biomedical researcher associated with MD Anderson. There are also public records for a Konstantin Sokolov identified as an artist, a professional hockey player and an AI-security specialist.
We are not suggesting that these people are automatically affected by the filings. Trademark rights are not that simple, and the existence of an application does not establish infringement.
But the coincidence is difficult to ignore.
The same applicant has sought protection for KONSTANTIN SOKOLOV, KONSTANTIN SOKOLOV MEDIA and KONSTANTIN SOKOLOV ARCHIVE, with the latter two extending across five classes that cover a remarkably broad range of digital and media activity.
Being Sokolov: What Is Actually Being Trademarked?
That is the interesting question. A trademark application does not tell us why it was filed. It does not prove an intention to interfere with this website, and we are not going to invent one.
What it does tell us is what someone decided was worth filing for.
Seven applications. Two media marks. Five classes each.
And, sitting in the middle of them, KONSTANTIN SOKOLOV ARCHIVE.
We began investigating Bank of London’s business and corporate structure a few weeks ago. Our starting point was the bank’s connection to Konstantin Sokolov, traced through his affiliated Swiss financiers — Alfred Moeckli and Ariel Sergio Davidoff — and through the Q2 2026 corporate resolution signed by TBOL members, including Sokolov himself and his mother.
TBOL Holdings Jersey Limited, registration number 151277 was identified as the sole upper holding company — the entity whose board members are the ultimate decision-makers for the entire TBOL group, including the operating bank.
At first, the shareholder structure of the Jersey-registered company was unavailable to us. Jersey — for those unfamiliar — is a Crown Dependency in the Channel Islands, not part of the United Kingdom, with its own company law and its own registry. We did not know where to look, or whether the information was accessible at all. Then our lawyers read the local legislation. And here is what they found – obtaining a shareholder register from a Jersey-registered company is remarkably easy.
Under Article 45(1) of the Companies (Jersey) Law 1991, the register of members must be open to inspection by any person during business hours, on payment of a fee not exceeding the published maximum.
45 Inspection of register
(1) The register of members shall during business hours be open to the inspection of a member of the company without charge, and of any other person on payment of such sum (if any), not exceeding the published maximum, as the company may require.
(2) A person may –
(a) in the case of any company, on payment of such sum (if any), not exceeding the published maximum, as the company may require; and
(b) in the case of a public company, on submission to the company of a declaration under Article 46,
require a copy of the register and the company shall, within 10 days after the receipt of the payment and (in the case of a public company) the declaration, cause the copy so required to be available at the place where the register is kept, for collection by that person during business hours.
(3) If inspection under this Article is refused, or if a copy so required is not made available within the proper period, the company is guilty of an offence.
(4) In the case of refusal or default, the court may by order compel an immediate inspection of the register, or direct that the copies required be made available to the person requiring them.
Our lawyer sent a request to registry@jerseyfsc.org on TBOL Holdings Jersey Limited register of members and received a short reply confirming that the register is kept at the company’s registered office and is available upon request. They asked whether it could be provided electronically. It could. Within a few hours, the PDF of TBOL Holdings Jersey Limited register of members as of June 18, 2026 was in our inbox (download). Nor, to our surprise, was there any fee to pay. Let’s see it.
Who is The Big Man?
We have no idea why Konstantin Sokolov decided to become the largest individual shareholder in a UK bank — but he did.
It is also unclear why the register lists personal residential addresses for both Sokolov and his mother, rather than a corporate or nominee address, as is customary for shareholders of this size — or any of the US business addresses associated with his companies, such as IJS Investments or Dynamic Frontier. Sokolov’s registered address is residential, on Malta; his mother’s is a residential address in Gibraltar. We are not publishing the specific addresses here, but the full register — which we obtained lawfully under Article 45 of the Companies (Jersey) Law 1991 — is attached for anyone who wants to verify this themselves.
Sokolov holds 399,122,220 ordinary shares in TBOL Holdings Jersey Limited — 8.28% of the company. His mother, Bronislava Gorelik, owns 391,263,039 shares — 8.12%. Individually, both sit just below the 10% threshold at which the PRA’s controller regime kicks in under Part XII of FSMA 2000. Together they account for 16.4%.
For context on why a residential address matters here: this is the same Konstantin Sokolov the Guardian identified in July 2026 as founder and chairman of the U.S. State Department’s $201 million TRIPP+ Enterprise Fund — a man the paper’s sources questioned specifically over “the ability to personally benefit from investment decisions.” A quasi-governmental appointee of this profile using a home address on a bank’s shareholder register, instead of the corporate infrastructure he otherwise operates through, is the kind of detail that invites the question, not answers it.
We would like to remind that Konstantin has a highly promising investment project — Pelagos Data Centres in Gibraltar — which we have written about many times. Just type PELAGOS in the search bar of our blog or click 1, 2, 3, 4, 5.
Add the two Cyprus companies the document itself flags as connected to Sokolov — ANALIKA LIMITED (9.41%) and ELISCANOUS LIMITED (4.81%) — and the bloc reaches 30.62%. The Sokolov link to ANALIKA and ELISCANOUS is our assessment (see our previous article), not the filing’s. The record shows names and shares — not ownership chains.
What the filing does confirm independently: of the 72.29% (2/3+) of shares that voted in favour of the 2Q 2026 capital resolution, the voting weight is concentrated in three shareholder groups — assuming the “probable connection” holds:
The Unattributed Group (first 3 members): Soata Limited + Buscelo Limited + PSInvest Capital Ltd — 28.63%
Tluszcz’s Group: Mangrove VI Investments Sarl + Mangrove V Investments Sarl — 12.99%
Anatomy of the Members: 55 Shareholders, Eight Countries, One Extraordinary Year
TBOL Holdings Jersey Limited has 55 shareholders. None of them holds 10% or more. The largest shareholder is Soata Limited with 9.635%. This keeps each holder below the 10% threshold at which the PRA’s controller regime would apply.
By geography, the ownership of Britain’s newest clearing bank looks nothing like Britain.
Jurisdiction
Holders
Share of capital
Cyprus
5
42.9%
United States
31
19.7%
Luxembourg
6
17.0%
Malta
2
16.4%
Cayman Islands
1
2.5%
Jersey
1
1.3%
Bermuda
1
0.3%
United Kingdom
3
0.01%
Five Cyprus-registered companies alone hold 42.9% shares of Bank of London that is more than every American venture fund that financed its launch, combined.
By type of holder, the register splits into 28 individuals, 14 companies, 10 funds, 3 charitable trusts/foundations.
By timing, the current cap table is far younger than the bank. Nearly 60% of it traces to just two quarters: Q2 and Q3 2025. That’s not when Bank of London launched (2021), and not when the April 2026 resolution was passed — it’s the window in which most of today’s ownership was quietly assembled, more than half a year before the public first saw any of these names.
The Participants We Flagged
Shaun Woodward — holds 8,572 shares (0.0000018%). A real, well-known former politician. Secretary of State for Northern Ireland (2007–2010), former Labour MP, and before that a Conservative MP who defected to Labour in 1999. He left the Conservative Party partly over its stance on LGBT rights.
Anthony Watson still holds 490,028 shares — 0.0001% of the company he founded. Five funding rounds and several ownership restructurings later, the man whose name is on the bank’s early press coverage owns a rounding error.
Victoria Raffé — holds 276 shares (0.00000006%). Former Director of Authorisations at the FCA, 20 years at the regulator (FCA/FSA), member of the Executive Committee, Chair of the Regulatory Transactions Committee, left in April 2015. She also served as a Director of The Bank of London Group Limited from November 2021 to October 2023 — before the change of control. After that — non-executive director at Starling Bank (a direct competitor of Bank of London!) and Reliance Bank.
Armen Grigoryan — holds 110 shares (0.00000002%). Secretary of the Security Council of Armenia from 2018 to August 2026, also Acting Foreign Minister in July–August 2021. Senior Advisor at PMCG, working on TRIPP. And that last point is the one that matters most. Konstantin Sokolov is the president of the TRIPP+ Enterprise Fund — a $201 million US State Department-backed vehicle for infrastructure projects in the South Caucasus. Grigoryan, a former Armenian security chief, now advises on TRIPP. This is not a “possible connection.” It is a direct intersection — the same project, the same fund, the same network.
Shaunt Sarkissian holds 4,888 shares (0.0000010%). Founder of Cortex MCP, later Head of Payments at Uphold and Chief Markets Officer at Bank of London. His father, Vahe Sarkissian, holds 8,677 shares (0.0000018%). Vahe is a Silicon Valley semiconductor veteran and former CEO and Chairman of FEI Company. Both are American entrepreneurs of Armenian heritage. In 2018, Uphold acquired Cortex MCP — explicitly including its patent portfolio. Today, part of that technology sits inside the Bank of London corporate structure. We’ll come back to the patents later — and what they reveal about Bank of London’s technology — in a separate piece.
If you have found anyone else worth a second look, tell us. We will happily add them to the list.
A company linked to a major Trump donor received authorization from the Treasury Department to complete an acquisition involving a sanctioned Russian bank, according to public records.
The Texas-based Dynamic Frontier Holdings purchased Teghut, one of Armenia’s largest copper mines, this summer. Dynamic Frontier’s manager is Konstantin Sokolov, a Russian-American businessman who was one of three dozen private donors to President Donald Trump’s $350 million White House ballroom project.
Photo: Donald Trump (impersonator) at the White House, Washington DC. Credit: Darren Halstead / Unsplash Source:Unsplash
Russia’s state-owned VTB Bank was Teghut’s primary shareholder and creditor prior to the purchase. The U.S. Treasury Department sanctioned VTB Bank following Russia’s invasion of Ukraine, describing it as a “critical artery” of the country’s financial system.
The sanctions prohibit U.S. companies and individuals from transacting with VTB Bank. But on Sept. 3, Dynamic Frontier said in a press statement that it had “received authorization from the U.S. Department of the Treasury” on June 1 to acquire all of Teghut’s shares and outstanding debt.
The Treasury Department’s Office of Foreign Assets Control, known as OFAC, can grant a license to individuals or companies to complete transactions that would otherwise be prohibited by sanctions. OFAC states on its website that it may grant a license to do business with sanctioned Russian entities when it is in the interest of the applicant and the U.S. government.
A spokesperson for Sokolov confirmed to ICIJ that OFAC granted a license to Dynamic Frontier to complete the acquisition of Teghut’s shares and debt. The spokesperson also said there was “no evidential basis” to draw any link between Sokolov’s donations and the approval of the license, and that any suggestion otherwise “would be incorrect and wholly misplaced.”
The Treasury Department did not answer questions about the license.
Armenia’s competition commission formally approved Dynamic Frontier’s acquisition of the mine on July 7. However, VTB’s deputy chairman said in an interview with Russian news agency Interfax that the bank sold its interests in Teghut to a “group of international investors” in June. The proceeds from the sale, the deputy chairman said, was 4 billion rubles, or roughly $46.5 million.
As far back as April, VTB’s chairman said that his bank was in “the final stages” of selling Teghut and Armenia’s Radio Azatutyun identified Sokolov as the mine’s likely buyer. In July, the buyer was reported to be a company founded by Sergei Virabyan, a former Armenian government official and banking executive. Virabyan refused to answer when asked whether Sokolov was the true owner of the mine, describing the information as a “commercial secret.”
In a statement, the spokesperson for Sokolov said Dynamic Frontier’s acquisition of Teghut “represents a long-term commitment to one of Armenia’s most strategically important mineral assets,” and that the company’s goal is to revitalize the mine and significantly increase its production. The transaction, the spokesperson said, “will help secure Armenia’s position and sovereignty in the critical minerals space.”
Sokolov was born in the Russian city of St. Petersburg in 1975 and immigrated to the United States at 21 years old, according to his personal website. In the late 2000s, he helped launch an investment fund that backed Russian real estate and hospitality projects.
Sokolov gave $2,300 to support Barack Obama’s presidential campaign in 2008, according to public records. But in more recent years, he has made large donations to Republican political causes. He donated $11 million in 2025 to MAGA Inc., a major pro-Trump super PAC, as well as making over a dozen other donations to other Republican campaigns and political groups. He also donated an undisclosed sum toward the new White House ballroom.
Sokolov was also appointed chairman this summer of a new $200 million State Department enterprise fund to oversee investments in the south Caucasus and central Asia. Armenia is expected to be a primary beneficiary of the fund.
In addition to Teghut, Sokolov has extensive business interests in Armenia’s banking and telecommunications sectors. In Armenia, some politicians have criticized the lack of transparency in his companies’ ownership structures and how he will manage his overlapping public and private roles.
Mesrop Manukyan, a member of Armenia’s National Assembly, told ICIJ that Sokolov’s position “create[s] legitimate questions about…the separation between private commercial interest and decisions involving public or government-backed funds.”
On 17 September 2026, we published Sokolov’s Shadow: The “Straight Man” Behind Bank of London’s Cleanup. That piece identified nine shareholders holding more than two-thirds of the shares in TBOL Holdings Jersey Limited (registration number 151277) — the ultimate parent of Bank of London.
In that article, we noted that each shareholder holds less than 25% — the disclosure threshold for Companies House. Four of them — Konstantin Sokolov, Bronislava Gorelik, ANALIKA, and ELISCANOUS — appear in the same register. Whether they act in concert is a separate question.
The Bank Control Question
For Companies House, the disclosure threshold for a controlling shareholder is 25%. That is the threshold our earlier piece addressed. But for the Prudential Regulation Authority (PRA), the relevant threshold is far lower: 10%.
Under Part XII of the Financial Services and Markets Act 2000 (FSMA), a person becomes a “controller” of a PRA-regulated firm — triggering mandatory notification and prior approval requirements — once they hold 10% or more of the shares or voting power in the firm or its parent undertaking. Crossing 20%, 30%, or 50% requires separate, additional approval each time. Proposed controllers must be assessed by the PRA for financial soundness and fitness and propriety before the acquisition takes effect — not after.
We do not know the actual percentage held by any of the nine shareholders named in the April 2026 resolution. TBOL Holdings Jersey Limited does not publicly disclose that breakdown, and we have not seen any document that does. One possible explanation for a structure involving multiple family members and affiliated entities is that it can result in individual holdings remaining below a regulatory disclosure threshold. We are not suggesting that this is what happened here. Without the underlying capitalization table, any specific percentage — 7%, 15%, 30% — would be a guess dressed up as a calculation. What we can say is narrower: a British bank’s ultimate ownership structure includes a family grouping and several Cyprus-registered entities whose combined position relative to the 10% PRA threshold is currently unknown to the public — and, as far as we can determine, to us.
UK-regulated firms are subject to a statutory controller regime requiring relevant controllers and changes in control to be notified to the appropriate regulator. Under Section 398 of FSMA, knowingly or recklessly providing the PRA with false or misleading information on a material matter is a criminal offence.
In our previous article, we did not mention one important detail: at the early stage of financing in 2021, alongside Mangrove Capital Partners, the launch of the innovative bank was also backed by ForgeLight— a US investment firm based in Miami, founded by former Viacom CFO Wade Davis, which led the $90 million round in November 2021 — and14W Venture Partners, a US venture capital firm that co-led the February 2023 extension.
While monitoring Caseboard.io, we came across a court record identified as BR-2025-000907, Watson v ForgeLight Holdings LP.
We should, however, make clear that we have not independently verified the information contained in the Caseboard.io entry. Accordingly, the screenshots are retained for transparency and as a record of what was publicly displayed on the platform at the time of publication. The entry should not be understood as establishing the nature or outcome of the proceedings.
Further information is expected to become available in Q1 2027.
(!) Updated screenshot from caseboard.io, 25 September 2026 — case details have changed.
TBOL: The Strong Decision 2026
Against the backdrop of everything we have gathered, the bank is undergoing serious changes. The Group Board announced and media dutifully repeated the news that it has been strengthened with the appointment of Noah Sharp as an Independent Non-Executive Director. Even The Banker wrote about it — Chris Newlands, a regular chronicler of the bank’s fortunes, covered the appointment in an article “Former NatWest non-executive director joins Bank of London board“. But Newlands did not mention one thing: after a long career at Deutsche Bank that ended 2018, Noah Sharp spent the rest of his professional life never staying anywhere longer than two years (Vodeno, NatWest Boxed, BCB Group, Paysafe (2.5Y), Standard Chartered).
Place your bets on whether his tenure at TBOL will last longer.
Rumoured Investors, Off the Register
In September 2024, Sky News reported:
“The new funding is understood to be being lined up from a number of investors including an entity called Aphorism Holding, according to the person.”
“Nada Hadadi, a wealthy investor who was suggested as being the primary source of the capital, has in fact only contributed a six-figure sum.”
The Financial Times, in September 2024, also reported on a mystery investor whom even the FT could not identify:
“The plot thickened on Saturday as rumours swirled about a mystery investor who was identified as both Nasser Hadidi and Nada Hadadi (if you know anything about this mystery man, do let us know, because we certainly have never heard of him).”
Compliance Corylated published two investigations in 2026 into the Bank and its investors, based on rumours. Both have since disappeared from their original URLs, surviving only in the Internet Archive.
What Britain Actually Regulates For
None of this is an argument against Bank of London existing, or against ambition. A modern clearing bank in London is a genuinely good idea — the UK could use more of them, and we’d like to see this one work. That’s not sarcasm.
But “good idea” and “good business” aren’t the same thing, and neither excuses what British financial regulation is designed to prevent: situations in which disclosure, control and regulatory oversight become unclear or difficult to verify. A jurisdiction that took hundreds of years to build a reputation for rule-following doesn’t get to relax that standard just because the pitch deck says “fintech” instead of “merchant bank.”
If the questions raised by Bank of London’s documentation, opaque ownership and financing history have innocent explanations — fine, let the PRA say so and clear the record. But if they amount to something, the consequence should land wherever the facts point, regardless of whose name is attached, how well-connected they are, or who they had dinner with once. That’s not a grudge against one bank. It’s the only version of “regulated” worth the word.
Very soon, we’ll go further down the rabbit hole — everything we uncover is legal and based on public information — and take a closer look at who owns what behind TBOL Holdings Jersey Limited. Stay tuned.
Bank of London is a British clearing bank and fintech company. It launched in November 2021 as the UK’s sixth principal clearing bank, entering the market with a $1.1 billion valuation.
Historically, the UK’s clearing market was dominated by four major banking groups: Barclays, HSBC, Lloyds and RBS (now NatWest). They were later joined by ClearBank and, in 2021, by Bank of London (also known as The Bank of London; TBOL).
An AI illustration inspired by the architecture of 77 Cornhill, London
“The Board recognise that, notwithstanding the commitment and ability of ultimate parent company shareholders to inject capital… a material uncertainty over going concern exists as a result of additional funding requirements and there are significant doubts about going concern.”
Qualified audit opinion from EY — two red flags:
Share-based payments: “Owing to significant turnover of staff and inadequate record keeping creating challenges to the retrieval of historical data, the Directors have been unable to conclude on the completeness, accuracy and disclosure of the share-based payment scheme records.”
Employment tax liabilities: “The Directors have also estimated the valuation, and based the accounting and disclosure of employment tax provisions arising from benefit in kind payments to employees, on the information they had available because of inadequate historical records.”
Office closures and legal claims:
“In October 2025, the Board decided to exit the Group’s Belfast office… impacted roles either relocated to London or transitioned to an outsourcing partner.”
“Provision in respect of a lease termination dispute… estimated exposure approximately £600k. Paid £129k into the Northern Ireland court… final settlement uncertain.”
The New York office was closed early. The London office at 77 Cornhill is the only one remaining, with the lease extended until 2031.
Anthony Watson Achievement: Britain’s First Gay Bank Founder
Anthony Watson’s story is not one of inherited privilege or a straight-line career. It is a story of a technologist who talked his way into banking, built a crypto exchange, and then founded a bank — while becoming one of the most visible LGBT+ figures in British finance.
His first job was in technical support at AOL Europe, followed by First-e (Europe’s first internet bank), Microsoft, later CIO for Europe/Middle East at Barclays, where he co-founded the global diversity & inclusion panel. Then Uphold/Bitreserve (a crypto platform startup).
He founded the project that launched as The Bank of London in November 2021. Companies House records show that Watson was a person with significant control and retained a 25–50% shareholding until April 2025. But Watson was not the one doing the quiet work. His key partner, Diane Elizabeth Gray-Smith, was the finance professional behind the early execution. As CFO at Uphold — the entity from which The Bank of London later emerged — she secured the Small Specialist Banking licence from the Bank of England before the 2021 launch.
Watson was the first British citizen on the board of GLAAD (since 2013), ambassador for the charity Stonewall, chairman of the European Diversity Awards. In June 2023, he received a CBE “for services to the LGBT community, equality and diversity”. A Bank of London statement celebrating the award described him as ‘Britain’s only gay bank CEO’ and ‘the first LGBT person in Europe to found a bank. It’s perhaps no surprise that with an openly gay CEO around 30% of senior leaders at The Bank of London identify as LGBT+. The Bank of London seeks to attract the “best diverse candidates for roles,” says Watson. “We don’t care if you’ve gone to university or not.”
According to an investigation by The Critic, Watson donated £340,000 to Labour and Labour politicians. The largest recipient of his donations was Dawn Butler, Shadow Equalities Minister; in 2018, she made him the head of her equality advisory committee.
Thus, Watson was the key founder and public face of the project, which had been developed for several years before The Bank of London launched in 2021. He stepped down as CEO in September 2024, as the bank entered a period of mounting financial and regulatory difficulties. He remained a shareholder and founder, however, and Companies House records show that he retained a 25–50% shareholding until April 2025.
Watson lost not only the bank, but the “The” in its brand. “The Bank of London” remains a registered trading name, but in the bank’s current logo and public communications, the “The” has been cut off — leaving simply “Bank of London” (rebranded by Conran Design Group in Q2 2025).
The Unicorn Bank Fed and Bled by Investors
Watson was the face of the bank. But the financing came largely from outside investors. And among the investors behind the project, one name appears particularly early — Mangrove Capital Partners. Mangrove was involved with TBOL long before the Bank of London became a public-facing banking brand. CB Insights, a commercial database that tracks private companies, funding rounds and investors, lists Mangrove Capital Partners as the only recorded investor for a separate entry for the company “Tbol.” The dates attached to that database entry are inconsistent, so they should not be treated as definitive proof of an investment in 2018. But the connection is consistent with Mark Tluszcz, Mangrove’s managing partner, joining the company’s board on 25 April 2018. That makes Mangrove an interesting starting point for tracing where the money behind the Bank of London actually came from.
November 2021 — $90 million Series C; $120 million raised to date. The Bank of London launched publicly with a $1.1 billion valuation, becoming what was described as the first pre-revenue bank to achieve “unicorn” status at launch. The latest round raised $90 million, led by ForgeLight, with follow-on investment from 14W Venture Partners and Mangrove Capital Partners. The company said it had raised $120 million in total by that point, with additional investment committed over the following 18 months.
February 2023 — $40 million Series C extension. The new round came from existing investors and brought the reported total raised to $160 million. Mangrove Capital Partners and 14W Venture Partners co-led the round, with ForgeLight also participating. Alex Zubillaga, managing partner of 14W and a Bank of London board member, was quoted on the transaction. Mark Tluszcz was identified as both managing partner of Mangrove and a board member of The Bank of London.
A coincidence worth noting. In February 2023, Harvey Schwartz became CEO of Carlyle Group — the firm co-founded by David Rubenstein, who also appears in our UChicago article. At the same time, Schwartz was Group Chairperson of The Bank of London. He had been associated with the bank since its launch.
August 2024 — £42 million funding round led by Mangrove. The round was closed in August, shortly before the HMRC issue became public. Mangrove Capital Partners led the oversubscribed round, making it the lead investor at a critical point in the bank’s history. The funding was announced on 9 September — after Watson’s departure and almost simultaneously with the HMRC controversy. The money was raised before the crisis, not alongside it.
September–October 2024 — the crisis becomes public. The bank faced an HMRC winding-up petition over unpaid taxes, while founder Anthony Watson stepped down as CEO and moved into an advisory role. Stephen Bell became CEO. The bank subsequently faced further scrutiny over its governance and capital position.
2025 — restructuring under new control. By the time the bank’s later accounts were being discussed publicly, the company described itself as operating under new ownership, having secured £57 million of Mangrove Capital-led funding, with a further £25 million committed. That £42 million was part of a broader £57 million injection from new owners led by Mangrove. The new management described the period as a comprehensive transformation of the business.
The Bank That Never Made a Penny
The 2025 accounts show the scale of the problem. The Bank of London Group Limited, the operating bank, reported a £23.5 million loss in 2025, following a £23.9 million loss in 2024.
At the Group level, the numbers are even worse. TBOL Holdings UK reported total income of approximately £6.4 million — including only £2.6 million in fee income — against a £27.0 million loss for the year. In 2024, the Group lost £46.9 million.
The bank operates a full-reserve model: it does not lend, and all client monies are held in full and unencumbered at the Bank of England. Its revenue is primarily fee-based, supplemented by interest income.
The contrast with the original launch story is striking. The bank entered the market with a $1.1 billion valuation, $120 million already raised, and plans to hire more than 3,000 people across the UK, Europe and North America. By 2025, the Group had approximately 86 employees, had never generated an annual profit, and had accumulated losses approaching £180 million.
Who Are Today’s Owners Trying to Fix This?
OPERATING ENTITY LICENSEDBY PRA – FRN 930379— THE BANK OF LONDON GROUP LIMITED, Company number 12844788 (formerly TBOL UK HOLDINGS LIMITED, 28 Aug 2020 — 08 Nov 2021).
One active person with significant control is indicated: TBOL Holdings UK Limited.
Current directors, according to Companies House — all six are also listed on the Bank’s official website:
BULLMAN, Antony George (CEO);
CARAWAN, Mark John (Independent Non-Executive Director & Chair of the Audit Committee);
HOWIE, Thomas Paul (General Manager & Executive Director);
MELIS, Anna Monique (Chairperson of the Board & Non-Executive Director);
MOECKLI, Alfred Walter (Non-Executive Member of Board);
WALKER, Simon Richard (Non-Executive Member of Board & Chair of Board of Risk Committee).
PARENT HOLDING COMPANY – TBOL HOLDINGS UK LIMITED, Company number 10511092. Former names: OPLYSE HOLDINGS LIMITED (11 Mar 2025 — 20 May 2026); THE BANK OF LONDON GROUP HOLDINGS LIMITED (12 Oct 2022 — 11 Mar 2025); TBOL LIMITED (25 Apr 2018 — 12 Oct 2022); TBOL PLC (08 Nov 2017 — 25 Apr 2018); UPHOLD GROUP PLC (05 Dec 2016 — 08 Nov 2017).
No active persons with significant control identified.
Only current officers: DAVIDOFF, Ariel Sergio, Dr (Appointed on 27 April 2026); MOECKLI, Alfred Walter (Appointed on 7 April 2026). Subscribers of our blog are already familiar with Swiss executives who have long-standing partnerships with Konstantin Sokolov and connections to Armenian AMIO Bank (1, 2). A quick look into the blog archives makes it clear: where you find this man, you find Konstantin Sokolov’s fingerprints.
A small off-topic that helps better understand the shareholder composition below. In our blog, we have always associated Cypriot companies under Konstantin Sokolov’s control with the administrative company GIF Capital LTD (Cyprus), offering administrative services, with Iryna Sidiropulu as the key officer. According to the investigation by hetq.am(our English translation at the link), Konstantin Sokolov’s mother is Bronislava Gorelik. She appears personally as a director in the Cypriot companies IFG Basis Capital Limited (Cyprus, HE 454994) and BASIS CAPITAL INTERNATIONAL FINANCIAL GROUP LTD (Cyprus, HE 454996), but the secretary of these companies is CAPLATINE SECRETARIAL LTD. The parent structure, Caplatine Ltd (Cyprus, HE 450799) was established recently, on 30 August 2023, and is officially a licensed Administrative Service Provider (ASP) under the direct supervision and regulation of the Cyprus Bar Association (website).
UPPER HOLDING COMPANY — TBOL HOLDINGS JERSEY LIMITED, Registration Number: 151277. Previous names: TBOL GROUP & HOLDINGS CORPORATION LIMITED (01/11/2023); FELLESSKAP GROUP & HOLDINGS CORPORATION LIMITED (11/02/2025 — 22/05/2026). Shareholders and owners are not disclosed in the public register. But the audited report 2025 of its UK subsidiary makes the power structure clear:
“The long term and strategic decision making for the organisation is the responsibility of the Company’s parent company, TBOL Holdings Jersey Limited, and the Group Board implements the decisions made by the Board of TBOL Holdings Jersey Limited.”
And now the most interesting part — our blog has obtained corporate records from Q2 2026 that allow us to determine with a high degree of certainty the controlling shareholder pool of TBOL HOLDINGS JERSEY LIMITED, with each shareholder holding less than 25% of the shares (below the threshold requiring disclosure).
TBOL HOLDINGS JERSEY LIMITEDSHAREHOLDERS:
KONSTANTIN SOKOLOV
BRONISLAVA GORELIK
ANALIKA LIMITED(Cyprus, HE 456247) — director Adamos Adamides, who is also a director of CAPLATINE SECRETARIAL LTD; secretary: CAPLATINE SECRETARIAL LTD.
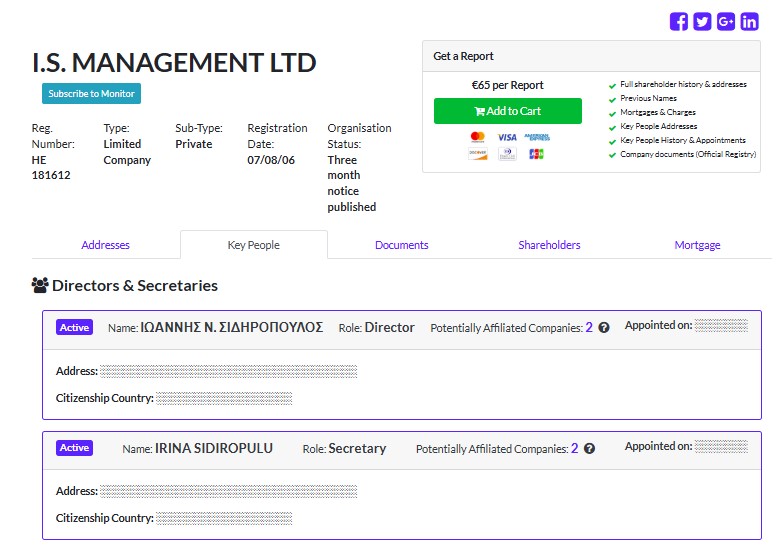
ELISCANOUS LIMITED (Cyprus, HE 446650)— director Ioannis Sidiropoulos (same surname — relative (?) of Irina Sidiropulu (GIF Capital), together they manage I.S. MANAGEMENT LTD (Cyprus, HE 181612), secretary ALNIA SECRETARIAL LIMITED (see above, associated with Caplatine Secretarial Ltd.)
Thus, we associate shareholders 1–4 with Konstantin Sokolov and his business network.
The UBOs of Cyprus companies 5–7 remain the mystery.
Shareholders 8–9: Mangrove Group — among the very first investors.
Interesting factsabout Mangrove.
Mark Tluszcz, founder of Mangrove Capital Partners, was a board member of TBOL Holdings UK Limited from 25 April 2018 — long before the public launch of the bank in November 2021 — and remained a director until 7 April 2026, when he left the board. Yet Mangrove entities — Mangrove V and Mangrove VI Investments Sarl, both managed by Tluszcz and Hans-Jürgen Schmitz — appear among the shareholders identified above. Tluszcz left the board; Mangrove remained in the capital.
Bank of London was never meant to make money. It was meant to be owned.
For Konstantin Sokolov — a Russian financier who donated his way into the US elite after the Ukraine invasion — this is not new. A strange bank, a messy balance sheet, a licence worth having — and then, quietly, a rewrite of the books, a change of name, a new face. We have seen it with the Armenian AMIO Bank. We are seeing it again here.
But look at the structure. Old investors stay. New ones appear. Sokolov’s people slip in between them. Nobody owns more than 25%. Nobody appears to control the bank — on paper. A perfectly fragmented cap table where no single name has to be disclosed.
And yet, decisions are made. Somebody is making them.
That is not a bank. That is a collection point — divided, diluted, and very carefully arranged.
In August 2026, the University of Chicago’s Board of Trustees announced its latest slate of new members. Five new trustees — successful and wealthy alumni of Chicago and other elite universities — were formally presented as a strengthening of the university’s governing body by distinguished community representatives. But university critics see a different dynamic at play: another round in a system in which the institution secures multimillion-dollar donations and pledges, while donors gain access to its leadership and its prestigious institutional seal.
David M. Rubenstein, chairman of the Board of Trustees, greeted the incoming members:
“We are pleased to welcome Wei, David, Stephanie, Imran and Konstantin to the Board. Their distinguished leadership and commitment will help guide the University through this pivotal moment as it embarks on the Chicago Minds campaign.”
AI-generated image; from left to right: Imran Siddiqui, Wei Cai, David M. Rubenstein, Konstantin Sokolov, Stephanie Rada Zocco, David Foley
Board Conductor
The Board of Trustees comprises 55 members. They are not elected by students or faculty; new trustees are elected by the Board itself. It is precisely this governance structure that has drawn criticism from UChicago United and other campus activist groups.
As a co-founder of the Carlyle Group, David M. Rubenstein is a central figure in this system: a University of Chicago Law School graduate, a trustee since 2007, and board chairman since 2022. His net worth is estimated at $4.2 billion, and Carlyle Group manages hundreds of billions in assets.
Rubenstein himself is a major donor to the university. He has contributed more than $61 million, and the David M. Rubenstein Forum bears his name. In March 2026, he pledged an additional $50 million for the renovation of Ida Noyes Hall, which will be renamed the David M. Rubenstein Commons.
Rubenstein’s public profile extends beyond philanthropy. His name appears in records linked to a 2012 meeting with Jeffrey Epstein at Carlyle’s offices, which his representatives describe as a brief conversation about philanthropy. In early 2026, Carlyle finalized a deal to acquire overseas assets of Russia’s Lukoil — a transaction that, given UChicago’s donor policies and the sanctions environment, raises questions about potential conflicts of interest. Rubenstein has also maintained contact with Donald Trump, whose administration has been a subject of scrutiny over its ties to business interests.
Student Critics of UChicago Management
In 2025, the student leftist advocacy platform UChicago United published a critical analysis of the university’s governance structure. The activists’ primary grievances center on the insularity of the Board of Trustees, which makes key decisions without student or faculty participation. Among the platform’s findings were a lack of financial transparency and accountability, and the fact that decisions on multibillion-dollar investments are made behind closed doors. This includes a $1 billion loss in endowment value over a single year (including $20 million in cryptocurrency); the acceptance of $12 million from a trustee whose company was later found to be fraudulent, with the university subsequently managing the fallout; and continued disregard for divestment calls from fossil fuels and the defense industrial complex.
Critics also point to budgetary imbalances: while academic departments face budget cuts, hiring freezes, and a shift toward ability-to-pay admissions criteria, the university continues to acquire land, maintain a large police apparatus, and spend $3 million on presidential residence renovations — more than the entire humanities research budget. A persistent gender pay gap has also been noted.
The Price of Admission: The New Trustees’ Resumes
IMRAN SIDDIQUI donated $3.5 million to the University of Chicago Center in Paris and established the John W. Boyer Professorship — a level of giving that opens doors to elite philanthropic circles. That academic positioning sits alongside a lengthy corporate dispute from his time at Apollo Global Management. Apollo accused Siddiqui of using confidential, proprietary information to secretly found a competitor, Caldera Holdings, while still an Apollo senior partner; a 2019 arbitration ruling found he had breached his fiduciary duties. The conflict resurfaced in 2025, when Apollo sued former executives for allegedly helping Siddiqui exploit company data — a claim Siddiqui disputes, having countersued for $1.5 billion. Neither the 2025 lawsuit nor the countersuit has been resolved. Siddiqui has since taken the helm of Talcott Financial. What the record does show is a pattern common across finance: a substantiated fiduciary breach did not end his career or bar him from continued industry leadership — nor, evidently, from a University of Chicago board seat. Whether that reflects the arbitration’s limited scope, the strength of his rebuttal in the ongoing case, or simply how forgiving elite institutions are toward donors with money to give, is a judgment call this article leaves to the reader.
WEI CAI is a former co-head of Goldman Sachs’ China division. He funded the Wei Cai Faculty in Residence program in Hong Kong and made a $125,000 anniversary contribution, effectively securing his place among the institution’s highest donor circles. His subsequent early retirement in January 2026 at the age of 59 marked the conclusion of an eight-year tenure navigating the complex intersection of Wall Street capital, strict regulatory compliance, and Beijing’s domestic security apparatus. In the Chinese financial sector, executives of this caliber operate under the direct oversight of the Chinese Communist Party (CCP), which increasingly enforces rigid anti-corruption campaigns and tight capital flight controls. While public records attribute his departure to a standard retirement, some observers have questioned whether such academic philanthropy by former state-linked financial executives serves broader soft-power aims. This high-profile positioning occurred against the backdrop of significant institutional vulnerabilities for Goldman Sachs in Asia. Specifically, the firm faced severe global scrutiny for its role in the $4.5 billion 1MDB sovereign wealth fund scandal in neighboring Malaysia, which resulted in billions in regulatory penalties, corporate leaks, and unprecedented compliance lawsuits.
DAVID FOLEY is a senior managing director at Blackstone Energy Transition Partners. Together with his spouse, he made a foundational gift to the Institute for Climate and Sustainable Growth, endowed two professorships, and sponsors an annual lecture series. His prominent academic positioning at the University of Chicago occurs against the backdrop of immense institutional vulnerabilities regarding corporate greenwashing and fossil-fuel investments. In the private equity sector, global energy heads operate under a conflicted dual mandate to capture green-transition capital while simultaneously extracting massive value from legacy hydrocarbon portfolios. Specifically, Foley serves as Chairman of the Advisory Council for the very institute he funds. This structural entanglement has drawn criticism given Blackstone’s extensive footprint in carbon-intensive infrastructure, routinely tracked by independent oversight bodies like the Private Equity Climate Risks Project. Most notably, its portfolio giant, Tallgrass Energy, became entangled in controversial congressional scrutiny over U.S. corporate maneuvers to secure massive drilling concessions in Venezuela following the geopolitical upheaval of early 2026. This blunt commercial pursuit of heavily sanctioned, heavy crude reserves exposes a profound disconnect between the climate-conscious narrative Foley promotes in academic halls and Blackstone’s multi-billion-dollar fossil fuel arbitrage.
STEPHANIE RADA ZOCCOhas donated to the university continuously for more than 30 years, graduated with her bachelor’s degree in 1988, and has held senior volunteer leadership positions since 1999.Her family resides in the Swiss commune of Anières, near Geneva, and her philanthropic record is longstanding. But her election to the Board also brings renewed attention to the financial mechanics of her spouse, Index Ventures co-founder Giuseppe Zocco. This is not a legacy of “old money,” but a fortune built on the lucrative arbitrage of tech-sector IPOs. Zocco aggressively championed foreign capital entry into autocratic markets, publicly stating that “Russia looks poised to become the next hot destination for foreign VC investment” (2007) during his multi-decade positioning on the board of e-commerce giant Ozon. Under his leadership, Index Ventures built a portfolio that included some of the most recognizable names in tech: Skype, Zendesk, Moleskine, and Ozon itself. Following the geopolitical fallout and strict sanctions regimes, Index Ventures executed a calculated total exit from its remaining Russian tech holdings. To shield this highly volatile, public-market liquidity, the family leverages strategic Switzerland-based asset structures. By channeling millions through Geneva-headquartered entities like The Rada Zocco Foundation, they systematically optimize global tax liabilities through structures that also carry favorable tax treatment. Ultimately, this strategic positioning highlights the sophisticated deployment of offshore financial mechanics to solidify elite institutional influence.
KONSTANTIN SOKOLOV in 2025 made a $100 million gift to the Booth School of Business, which led to the Executive MBA program being renamed the Sokolov Executive MBA Program in his honor. Sokolov’s recent transaction transferring ownership of the Teghut copper mine from sanctioned Russian control to U.S. ownership has drawn scrutiny. Critics have suggested that his affiliation with UChicago may have played a role in the transaction’s viability.
We now know who these five new trustees are. But to understand the significance of their arrival on the Board, one must look at what they will oversee: the university’s financial system, its $10.9 billion endowment, its multibillion-dollar debt load, and what critics describe as one of the most opaque governance systems in American higher education.
Between April 2019 and May 2021, FTI Consulting provided expert economic consulting services to VTB through a Singaporean law firm intermediary. Invoices went unpaid for 90, 99, and even 198 days, which OFAC classified as prohibited “new debt” . OFAC’s message was clear: you cannot do indirectly what you cannot do directly .
FTI agreed to pay $1.05 million to settle the case.
Now, the Punchline
On the very same day — June 1, 2026 — OFAC publicised the FTI penalty. And on that same date, Dynamic Frontier Holdings stated it had received authorization from the U.S. Department of the Treasury to acquire 100% of Teghout CJSC’s shares and its outstanding debt .
One American company was fined for indirectly dealing with VTB. On the same day, another American company says it received Treasury authorization to acquire a VTB-linked asset worth hundreds of millions of dollars. The first decision is public. The second is not.
We searched the Treasury and OFAC records for June 1. What we found was the $1.05 million FTI Consulting settlement. What we did not find in the public OFAC records was the Treasury authorization that Dynamic Frontier says it received that day.
The authorization may exist as a private license, which OFAC does not publish. But until it appears, the contrast is striking.
Bottom line: One company was penalized for indirect VTB dealings; another says it was authorized to acquire a VTB-linked asset. On the same day. Make it make sense.